Roof condition
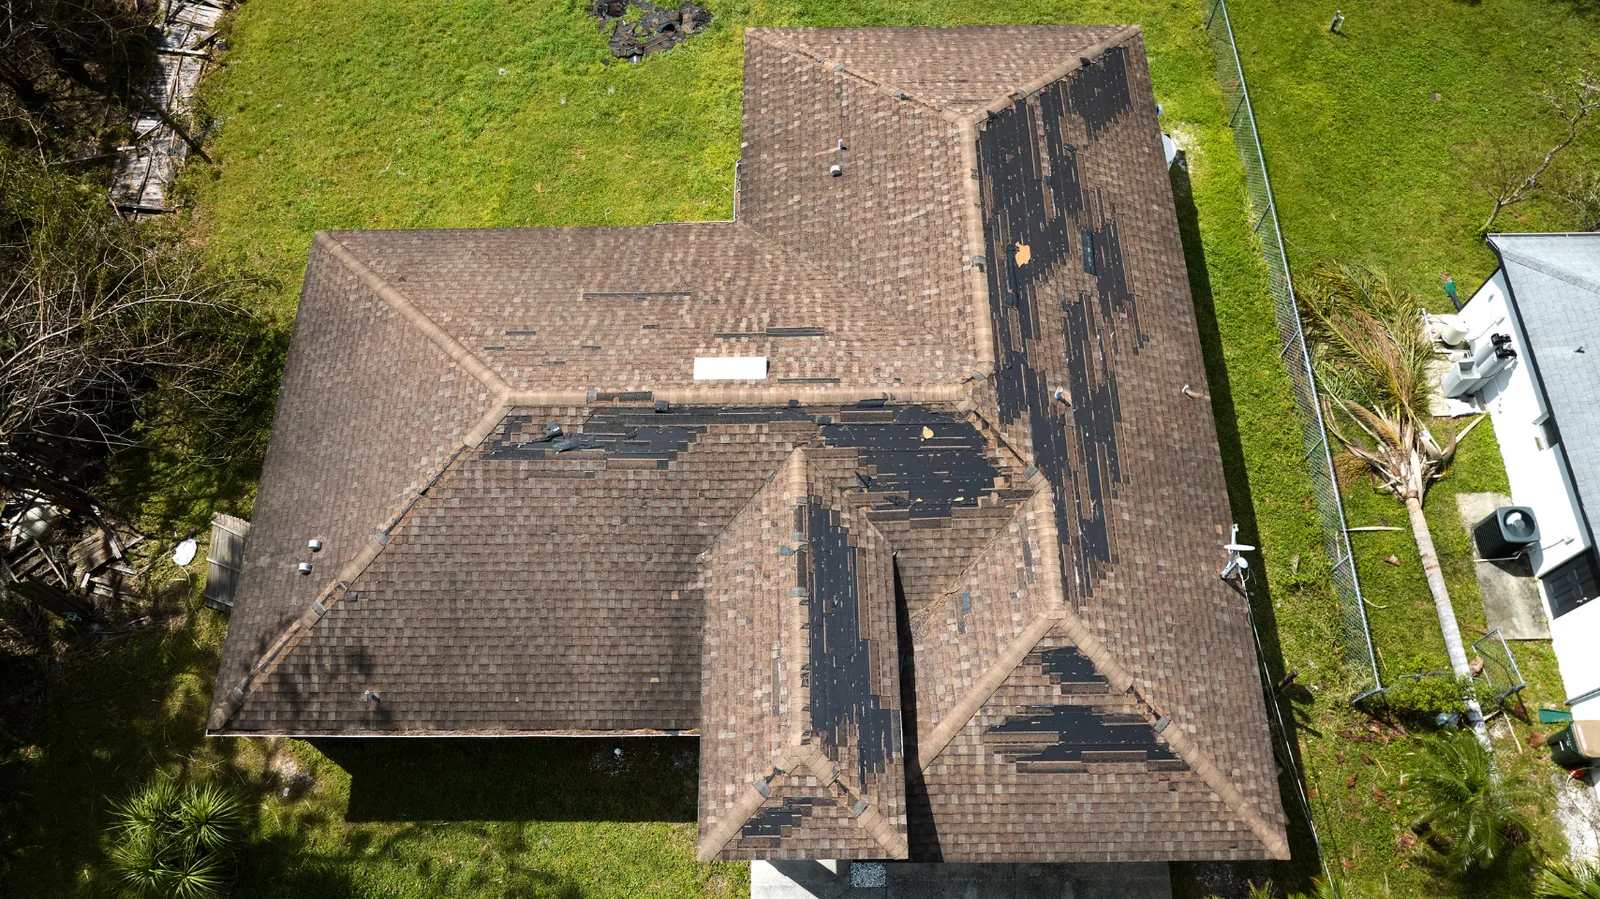
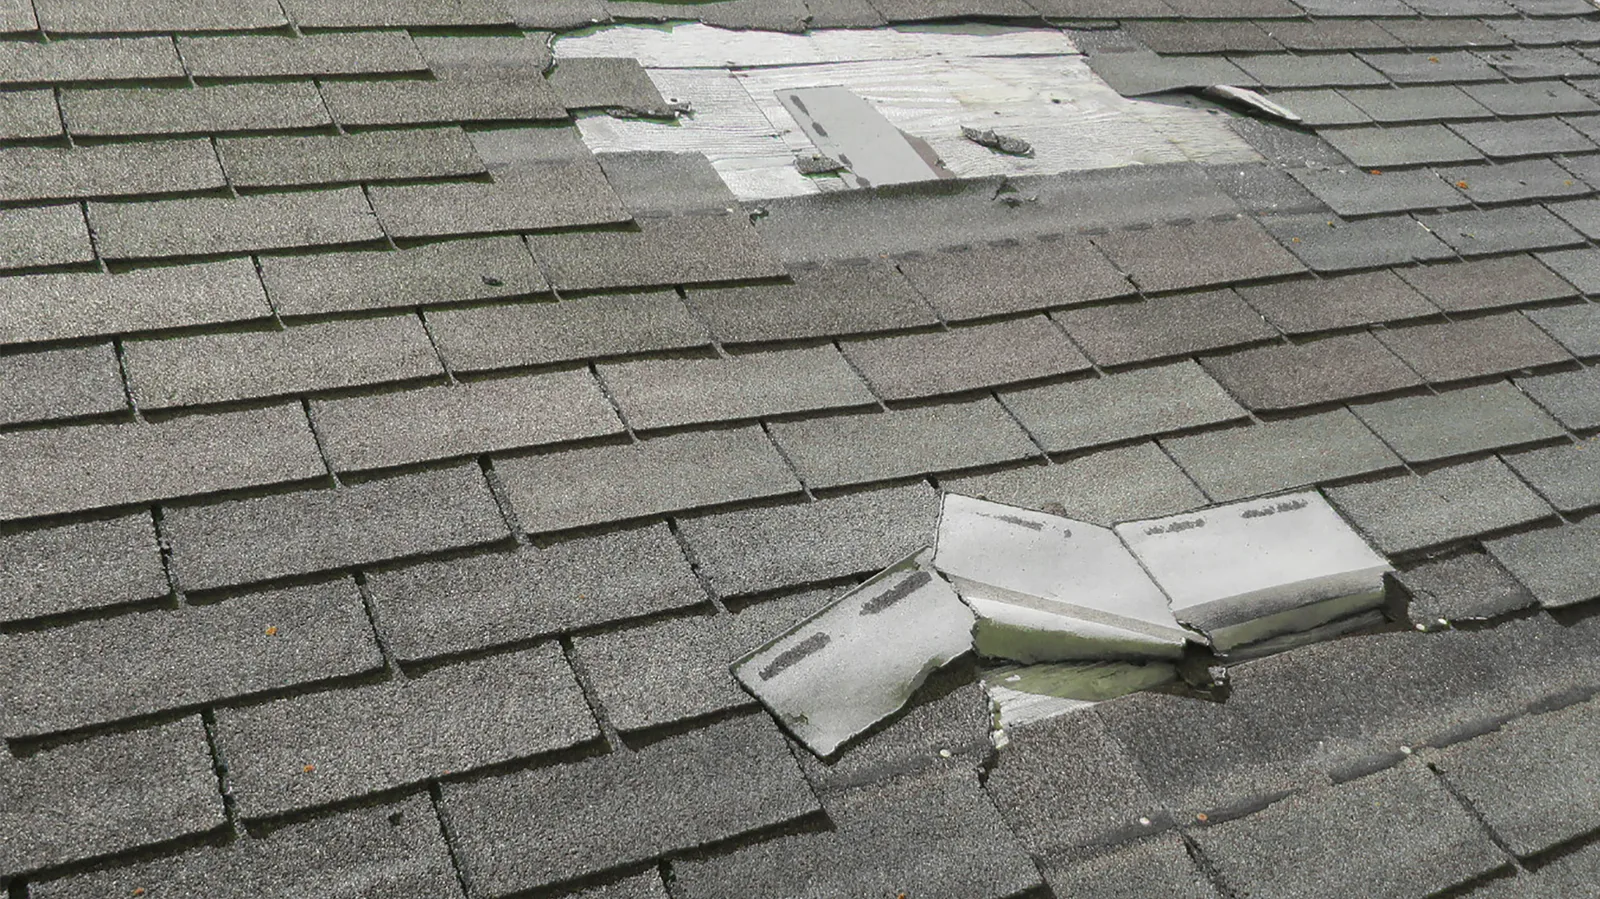
Missing, creased or impacted material needs examination with its adjoining layers and details. The physical condition determines what construction work is needed.
Roeland Park, KS
A roof inspection explains condition and physical repair scope. Your policy and the insurer’s claim decision determine coverage and payment.
Free roof inspections. Repair and replacement options explained.
Storm damage creates two conversations: the roof work needed and the policy response. This guide explains that separation and the payment vocabulary that can affect the owner’s budget. It is general guidance; the actual policy and claim control.
One does not automatically establish the others.
Missing, creased or impacted material needs examination with its adjoining layers and details. The physical condition determines what construction work is needed.
A nearby report describes weather at its recorded location, rather than proof of damage at the property. History and evidence help evaluate cause; an inspection alone cannot date every mark.
Coverage depends on the policy, cause and claim terms. Age and wear are different from a covered event. A repair budget or a nearby storm does not guarantee payment.
Read the policy terms with the insurer’s actual decision.
The deductible is the portion assigned to you under the applicable claim terms. A roofing price above that amount alone does not establish coverage or settle what the insurer will pay.
Actual cash value takes depreciation into account under the policy. Replacement cost provisions can involve later payments after qualifying work and documentation. The specific policy controls how those terms operate.
The insurer’s covered scope, recoverable or nonrecoverable depreciation, exclusions and limits affect payment. A contractor’s construction scope and the insurer’s coverage decision have different roles.
Call and say where water is entering. Keep away from wet electrical fittings and unsafe areas, and stay off the roof. Temporary protection limits exposure while a permanent repair is planned. For a possible claim, notify the insurer promptly and follow the policy’s reporting and damage-protection requirements. A roofer explains the condition and work without promising the insurer’s outcome.
Age alone does not establish a covered claim. Policy language and the cause of damage determine coverage, and payment terms affect the owner’s share.
No. The estimate describes construction work. The insurer applies the policy to the actual claim.
No. Reports describe events at recorded locations and times. Property-specific evidence and the policy matter.
Roeland Park Roofing Co
Tell us where the property is and what needs attention. Call (913) 270-1748 or request a free inspection. We can start with what you have noticed and work through the options from there.
(913) 270-1748